- /
Should You Sell a House Without a Realtor in Florida? FSBO Advantages, Risks, and Dangers
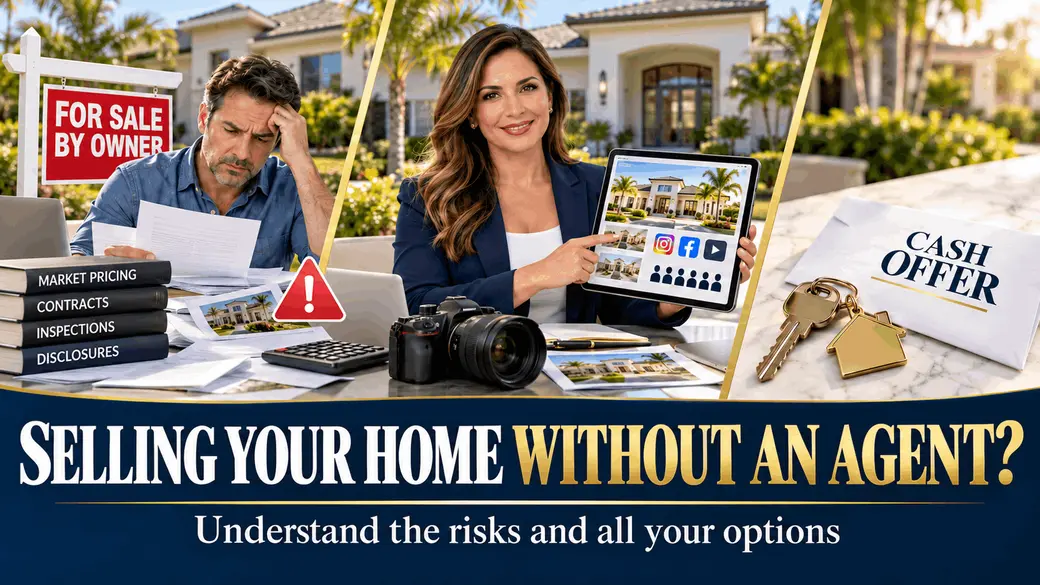
Selling a property as For Sale by Owner (FSBO) means that the homeowner attempts to manage the sale without hiring a real estate agent to represent them as the seller.
The idea may sound simple: advertise the house, find a buyer, sign a contract, and save money. It can work in certain limited circumstances. However, selling without an agent does not eliminate the professional work required by a real estate transaction. It makes the owner responsible for completing that work, coordinating it, or hiring separate professionals.
The greatest danger is not always that the house will fail to sell. The owner might sell below market value, accept an offer that cannot close, fail to satisfy a disclosure obligation, miss a contractual deadline, become exposed to fraud, or discover too late that the expected savings disappeared through credits, repairs, expenses, and preventable mistakes.
Before deciding, compare the potential savings with the price, time, risk, and estimated net proceeds associated with each strategy.
If you are still organizing the process, read our Complete Guide to Selling a House in Florida, review how much it costs to sell a house in Florida, and learn which repairs may be worth completing before selling.
Are you considering selling on your own? Request a free property valuation before setting the price. Understanding the probable value, current competition, and estimated net proceeds can help you decide based on numbers—not only on the expectation of saving money.
The Small Advantages of Selling For Sale by Owner
FSBO can offer some benefits, especially when the owner already has experience, knows the buyer, or is handling a relatively simple transaction.
1. Potential Reduction of Certain Fees
The owner may avoid or reduce the compensation associated with a listing agent. However, this does not mean the sale will be free or that all real estate compensation will necessarily be eliminated.
Expenses may still include:
- Marketing and professional photography.
- Placement on certain portals or flat-fee MLS services.
- An attorney, title company, or closing agent.
- Inspections, repairs, and certificates.
- Compensation or concessions associated with a represented buyer.
- Taxes, HOA charges, estoppel fees, liens, and other closing costs.
Real estate commissions and compensation are negotiable. The correct analysis compares final net proceeds, not an isolated percentage.
2. Direct Control Over the Process
The owner decides how to present the home, when to show it, and how to communicate with interested parties. Some sellers value that control, particularly when they have the availability and negotiation experience required.
3. Personal Knowledge of the Property
No one knows a home as well as the person who lives there. The owner can explain improvements, neighborhood features, and practical details. The challenge is turning that personal knowledge into an objective, verifiable presentation focused on what the market actually values.
4. It May Be More Practical When a Buyer Already Exists
If a relative, neighbor, tenant, or acquaintance already wants to purchase the property, a full market launch may be less necessary. Even then, the seller should determine the property's value, verify financing, document the terms, and use the appropriate professionals for the contract, title work, and closing.
The Reality: A Seller Without an Agent Assumes Multiple Roles
A residential sale involves much more than placing a sign in the yard. The owner may end up serving simultaneously as:
- Pricing analyst.
- Marketing specialist.
- Photography and property-preparation coordinator.
- Advertising and inquiry manager.
- Buyer-screening contact.
- Showing coordinator.
- Negotiator.
- Contract and deadline administrator.
- Point of contact for the inspection, appraisal, insurance, and financing.
- Coordinator with the title company, HOA, municipality, and closing agent.
- Person responsible for collecting documents and disclosures.
Some of these services can be hired separately, but doing so reduces the expected savings and requires the seller to coordinate professionals who may not be responsible for managing the entire transaction.
The Value of an Agent With a Strong Reputation, Experience, and Proven Exposure
It is important to clarify that not all agents provide the same level of service, experience, or exposure. Hiring someone merely because they hold a license does not automatically produce a better sale.
The real value appears when a seller works with an agent who has built an established career, has verifiable results, understands the market, anticipates problems, and has a genuine platform for presenting the property.
1. Reputation Creates Confidence From the First Contact
A strong reputation is not built through a single social-media post. It develops through years of work, completed transactions, satisfied clients, and professional relationships.
When buyers, agents, lenders, title companies, and other participants recognize that a listing is being managed by a serious professional, they may have greater confidence that:
- The information was prepared correctly.
- Inquiries will receive follow-up.
- Offers will be evaluated objectively.
- Documents and deadlines will be addressed.
- Negotiations will be handled professionally.
- Problems will not be ignored until the last moment.
Reputation does not replace a good property or guarantee a sale, but it can reduce uncertainty and encourage other parties to take the listing more seriously.
2. An Established Career Helps Identify Problems Before They Become Crises
Experience involves much more than knowing how to complete forms. It comes from seeing enough transactions to recognize warning signs.
An experienced agent may notice that a preapproval does not appear compatible with an offer, that an older roof could create insurance issues, that a concession may exceed the loan program's limits, that a contractual deadline is dangerous, or that an HOA, title, or permit issue requires immediate investigation.
That ability to anticipate complications can protect weeks of marketing, prevent a cancellation, and reduce the likelihood of discovering a serious problem shortly before closing.
3. Exposure Should Not Depend Only on the MLS
The MLS is an extremely important tool, but it is not a complete marketing plan by itself.
An agent with a strong social-media presence can present the property to thousands of additional people, generate conversations, identify potential buyers, and create multiple opportunities for engagement around the listing.
The difference is not simply posting one photo. An established platform may provide:
- An audience that already recognizes and trusts the professional.
- Video content, photography, stories, and campaigns.
- Organic reach and targeted advertising.
- Presentation of the property in English and Spanish.
- Distribution to local buyers, people moving to Florida, and investors.
- Follow-up with people who interact, ask questions, or show interest.
In my case, my digital presence and that of The Florida Team allow us to promote properties to a community of approximately 200,000 followers across different platforms, in addition to the extended reach each piece of content may generate.
4. An Active Database Can Create Immediate Opportunities
One of the greatest differences between advertising a property from scratch and working with an established team is access to an existing database.
An agent with years of marketing and follow-up may have buyers, sellers, investors, agents, and other contacts who have already expressed interest in particular cities, price ranges, or property types.
This makes it possible to:
- Identify buyers whose criteria match the property.
- Notify people who have already searched in that area.
- Promote the listing to agents with active clients.
- Follow up with prospects who have not yet found the right home.
- Use engagement data to prioritize genuine opportunities.
The Florida Team has a database of approximately 10,000 leads and contacts, along with follow-up systems designed to detect activity and interest. This does not guarantee that every property already has a buyer waiting, but it creates a distribution and follow-up advantage that an owner would normally have to build from the ground up.
5. Previous Results Help Build a Better Strategy
An agent with a proven record can use experience from prior transactions to prepare, position, and negotiate the property.
Our team has participated in more than 100 closings during the past 12 months. Every transaction provides information about buyer objections, inspections, appraisals, insurance, financing, credits, repairs, and problems that may arise before closing.
That experience helps answer important questions:
- Which repairs could increase buyer interest, and which may be unnecessary expenses?
- How could the roof affect the buyer's insurance?
- What type of financing might work for the property?
- Which terms make an offer truly strong?
- When is it better to repair, provide a credit, or maintain a firm position?
- How do the estimated net proceeds of multiple offers compare?
6. Professional Negotiation Protects the Seller's Net Proceeds
The best agent is not necessarily the one who promises the highest price to obtain the listing. It is the professional who can justify a strategy, generate exposure, interpret the market's response, and protect the seller's position throughout each negotiation.
That includes evaluating the deposit, financing, inspection, appraisal, credits, contingencies, and probability of closing. It also means knowing when room for negotiation exists and when an apparent concession may protect a much more valuable transaction.
7. The Seller Receives a Complete Structure, Not Just a Listing
Working with an experienced agent and an organized team can provide coordination among marketing, showings, buyers, agents, the lender, title company, HOA, inspection, and closing.
The owner retains all final decisions without having to become solely responsible for chasing documents, interpreting every communication, and remembering every deadline.
When comparing FSBO with professional representation, do not ask only how much the agent charges. Also consider:
- Reputation and verifiable results.
- Marketing plan.
- Social-media reach.
- Size and quality of the database.
- Knowledge of financing and insurance.
- Negotiation ability.
- Systems and team supporting the sale.
- Attention and follow-up the property will receive.
An agent with little exposure, weak follow-up, and no clear strategy may provide limited value. However, a professional with an established career, an existing audience, and proven systems can make a meaningful difference in exposure, negotiation, security, and net proceeds.
Risk 1: Setting the Wrong Price
Pricing is one of the most significant FSBO risks.
An owner may overvalue the home because of completed improvements, personal memories, the mortgage balance, or the amount needed to purchase another property. The owner may also undervalue it to produce a fast sale without knowing how much the market might have paid.
Online portals may provide an initial reference, but they do not replace a detailed analysis of:
- Recent closed sales.
- Active and pending properties.
- Condition, size, lot, and location.
- Pool, garage, roof, and upgrades.
- HOA, restrictions, and community type.
- Concessions given to buyers.
- Market trends and average time to sell.
An excessively high price can reduce initial interest, increase days on market, and create the impression that something is wrong. A price that is too low may produce a fast sale while leaving a significant amount of money on the table.
Risk 2: Confusing the Sales Price With Net Proceeds
Accepting a $500,000 offer does not mean receiving $500,000.
The following may be deducted from the sales price:
- Mortgage payoff and other loans.
- Taxes and prorations.
- Title and closing costs, depending on the transaction.
- Liens, permits, fines, or outstanding balances.
- Estoppel fees and HOA or condominium charges.
- Repairs and credits.
- Buyer concessions.
- Property-preparation and marketing costs.
- Agreed compensation.
Two offers with the same price can produce very different net proceeds. A higher offer with weak financing, large concessions, and extensive contingencies may be less attractive than a lower-looking offer with stronger terms.
Risk 3: Limited Exposure and Insufficient Marketing
Posting a house on social media or a portal does not guarantee that it will reach the right buyer.
A professional strategy may include photography, video, copywriting, distribution, MLS positioning, communication with agents, digital campaigns, open houses, prospect follow-up, and adjustments based on the market's response.
The owner should ask:
- Where will the property appear?
- Will its information be distributed correctly?
- Do the photographs compete effectively with other listings?
- Who will respond quickly to each inquiry?
- How will visitors receive follow-up?
- How will the seller determine whether the problem is price, presentation, or exposure?
Less exposure can mean less competition among buyers and weaker negotiating power.
Risk 4: Not Knowing Whether the Buyer Can Actually Close
Not every interested person is prepared to purchase.
Before opening the door or accepting an offer, verify:
- A current and reasonable preapproval.
- Proof of funds for the down payment and closing costs.
- Evidence of available funds for a cash purchase.
- A loan program compatible with the property.
- Ability to cover an appraisal gap, if offered.
- A legitimate source for all submitted documents.
A preapproval letter does not guarantee closing. The buyer may still encounter issues involving credit, income, assets, insurance, appraisal, HOA requirements, or underwriting.
As a REALTOR® and Mortgage Loan Originator, one of my greatest advantages when representing a seller is the ability to evaluate not only the offered price, but also the financial structure and potential obstacles that could prevent closing.
Risk 5: Personal Safety and Loss of Privacy
FSBO sellers often publish their personal phone number and coordinate visits with strangers. This can reveal schedules, family information, the contents of the home, and times when the property is vacant.
Basic precautions include:
- Verifying identity and contact information.
- Requesting a preapproval or proof of funds before a showing.
- Avoiding showing the property completely alone.
- Securing documents, medication, jewelry, keys, and personal property.
- Not disclosing family routines or financial information.
- Maintaining a record of every visit.
- Using secure access and lock-up procedures.
Enthusiasm from a supposed buyer is not a substitute for verification.
Risk 6: Advertising or Treatment That Could Create Fair Housing Problems
Advertising, questions, and buyer selection must comply with applicable fair housing laws. An owner can make mistakes by describing the “ideal buyer,” asking inappropriate personal questions, or applying different criteria to different prospects.
HUD's official Fair Housing information explains federal protections related to race, color, national origin, religion, sex, familial status, and disability.
Decisions should be based on the objective terms of the offer and the buyer's ability to perform under the contract—not on protected characteristics.
Risk 7: Incomplete or Incorrect Disclosures
Selling “as-is” does not mean that an owner may conceal known problems.
Florida sellers may have obligations involving known facts that materially affect the property's value and are not readily observable. Depending on the home and transaction, documents or disclosures may also address:
- Leaks, moisture, or prior damage.
- Roof, structure, electrical system, plumbing, or air conditioning.
- Termites or other wood-destroying organisms.
- Permits, additions, conversions, or violations.
- HOA, condominium, assessments, and restrictions.
- Insurance claims or significant repairs.
- Flood risk or history.
- Lead-based paint in certain homes constructed before 1978.
Section 689.302 of the Florida Statutes establishes a flood disclosure for certain residential sales before or at the time the sales contract is executed.
For many homes built before 1978, the EPA explains the federal disclosure requirements concerning potential lead-based paint hazards.
A late, incomplete, or incorrect disclosure can affect negotiations, the contract, and potential liability after closing. When in doubt, consult a Florida real estate attorney or another properly licensed professional.
Risk 8: Using the Wrong Contract or Misunderstanding Its Deadlines
A sales contract includes much more than the price and closing date.
It may address:
- The deposit and deadline for delivery.
- Inspection period.
- Financing contingency.
- Appraisal and possible value differences.
- Title requirements.
- HOA or condominium approval.
- Sale of another property.
- Repairs, credits, and included personal property.
- Closing date and possession.
- Default, cancellation, and disposition of the deposit.
Copying a document from the internet or reusing an old contract can introduce terms that do not fit the transaction. A missed deadline or ambiguous provision can change the parties' rights, deposits, and obligations.
A real estate agent is not a substitute for an attorney. When legal interpretation, specialized language, or advice concerning legal rights is needed, consult a licensed Florida attorney.
Risk 9: Negotiating From an Emotional Position
Owners know every investment and sacrifice they have made in the property. As a result, a comment about the kitchen, roof, or asking price may feel personal.
Effective negotiation requires separating three things:
- The property's emotional value.
- The cost of completed improvements.
- What today's market is willing to pay.
It also requires evaluating the full offer: financing, deposit, contingencies, inspection, credits, dates, and probability of closing. Responding out of frustration or revealing the minimum acceptable price too early can weaken the seller's position.
Risk 10: Inspections and Repair Requests
After an offer is accepted, inspections may uncover issues involving the roof, moisture, electrical system, plumbing, air conditioning, termites, pool, septic system, well, or structure.
The seller must determine:
- Whether the issue is genuine and how extensive it is.
- Whether a contractor, permit, or additional evaluation is required.
- Whether it affects insurance or financing.
- Whether to repair, provide a credit, adjust the price, or reject the request.
- Whether the response complies with the contract and its deadlines.
Automatically accepting every request may unnecessarily reduce net proceeds. Rejecting everything without analysis may drive away a buyer who was fully capable of closing.
Risk 11: Appraisal, Financing, and Insurance
A property may be under contract and still fail to reach closing.
Common problems include:
- An appraisal below the contract price.
- A roof or systems that make insurance difficult to obtain.
- Repairs required by the loan program.
- An HOA that is not approved or has missing documents.
- A change in the buyer's financial circumstances.
- Unresolved underwriting conditions.
- Insufficient credit or unverifiable funds.
The seller should understand which contingencies protect the buyer, when they expire, and what options exist if a problem arises.
Risk 12: Title, Lien, Permit, or Authority-to-Sell Problems
Issues discovered before closing may include:
- Liens or judgments.
- An old mortgage without a recorded release.
- Inheritance or probate matters.
- Divorce or additional owners.
- Errors in names or the deed.
- Open permits.
- Municipal violations.
- HOA balances or assessments.
- Survey, access, or boundary problems.
Not all of these issues can be resolved in a few days. Discovering them late may delay or prevent closing and generate additional expenses.
Risk 13: Fraud, Impersonation, and Changes to Wire Instructions
Real estate transactions attract fraud because they involve large sums of money and numerous emails among buyers, sellers, agents, lenders, and title companies.
Never trust a change in wire instructions received only by email. Verify it using a known, independent telephone number. Do not send funds or sensitive information in response to an unexpected message.
The FBI Internet Crime Complaint Center provides information about Business Email Compromise and fraud that can redirect legitimate wire transfers.
Risk 14: Investing Too Much Time Without Obtaining a Better Result
The owner must answer calls, screen casual prospects, coordinate schedules, prepare the home, follow up, review offers, and manage every stage while continuing to handle work and family responsibilities.
Time also has a cost. If the property remains on the market longer, mortgage payments, taxes, insurance, HOA fees, maintenance, and other expenses can accumulate. Saving a fee while losing months or accepting a substantial price reduction does not necessarily produce a better outcome.
Risk 15: Receiving Lower Net Proceeds Even After “Saving” the Commission
The goal should not be to spend as little as possible on the sale. It should be to retain the best possible net result at an acceptable level of risk.
A seller might save on representation while also:
- Pricing below what the market could have supported.
- Providing unnecessary credits.
- Selecting a weak offer.
- Losing exposure and competition.
- Spending more time carrying the property.
- Paying for services separately.
- Encountering a contract or disclosure error.
The correct comparison is:
Probable sales price − expenses − credits − repairs − carrying costs − risk = actual result
When Might FSBO Make Sense?
Selling without an agent may be more reasonable when:
- A serious and verifiable buyer already exists.
- The property and title are relatively straightforward.
- The seller understands the process and can dedicate sufficient time.
- A reliable valuation is available.
- An attorney and title company participate when appropriate.
- Disclosures and documents are organized.
- The seller can manage showings and negotiations safely.
- The seller does not depend on an immediate sale to complete another purchase.
Even under these circumstances, it is wise to compare projected net proceeds and obtain guidance before signing anything.
Options Between FSBO and Full Representation
The choices are not limited to doing everything alone or hiring a full-service agent. Depending on the market and the seller's needs, alternatives may include:
| Option | What It May Provide | What Remains the Seller's Responsibility |
|---|---|---|
| Direct FSBO | Maximum control and possible reduction of fees | Pricing, marketing, showings, security, negotiation, documents, and coordination |
| Flat-fee MLS | Basic MLS placement according to the selected service | Listing quality, inquiries, negotiation, contracts, and closing |
| Limited service | Help with particular tasks | Everything not expressly included |
| Full representation | Strategy, marketing, coordination, negotiation, and follow-up | Final decisions and compliance with the seller's obligations |
Carefully review what each service includes, who represents your interests, and who will be responsible when a problem arises.
How to Reduce Risk if You Decide to Sell on Your Own
If you decide to attempt an FSBO sale, consider taking at least the following steps:
- Obtain a valuation and comparable-sales analysis.
- Request a preliminary net sheet.
- Consult a real estate attorney regarding the contract and disclosures.
- Select a reliable title company or closing agent.
- Investigate title, permits, violations, and HOA matters in advance.
- Organize documents concerning the roof, insurance, repairs, and major systems.
- Use professional photography and property descriptions.
- Establish a safety procedure for showings.
- Verify preapproval, proof of funds, and identity.
- Compare offers by terms and net proceeds—not only price.
- Create a calendar containing every contractual deadline.
- Verbally verify all wire instructions and sensitive changes.
- Do not conceal known defects or improvise legal answers.
Before Deciding, Compare Two Realistic Scenarios
Request two estimates:
Scenario A: Selling on Your Own
Include the probable price under the exposure you will actually obtain, advertising costs, professional services, time, possible concessions, and level of risk.
Scenario B: Selling With Representation
Include the pricing strategy, the agent's reputation, verifiable results, marketing plan, social-media reach, database, follow-up systems, services, negotiated compensation, offer management, and projected net proceeds.
The best decision is the one that produces the most favorable result after considering money, time, and risk.
What if You Still Do Not Want to Use an Agent?
After learning about the responsibilities and risks of selling on your own, you may still prefer not to hire an agent or go through a traditional process involving marketing, showings, inspections, and financing.
In that case, I can connect you with my network of investors, who can evaluate the property information and may present you with a cash offer in less than 24 hours.
This alternative may be convenient for owners who prioritize speed, privacy, and simplicity; do not want to complete repairs; have a property with complications; or want to consider a direct-purchase option before deciding what to do.
Requesting an offer does not obligate you to accept it. You can review the proposal, compare it with the probable value of a traditional sale, and decide which alternative best fits your priorities.
An investor offer is normally calculated differently from a sale exposed to the open market. For that reason, I recommend comparing not only the price, but also the repairs, time, expenses, terms, and net result of each alternative.
Obtain a Valuation Before Selling For Sale by Owner
You do not have to sign a listing agreement to obtain initial clarity.
I am Laura Rojas, REALTOR® and Mortgage Loan Originator, CEO and Team Leader of The Florida Team by LPT Realty. My team and I can help you evaluate:
- The property's probable value.
- Comparable sales and active competition.
- Repairs that could affect insurance or financing.
- Potential expenses and estimated net proceeds.
- The financial strength of offers.
- Marketing and negotiation strategy.
Discover how much your property may be worth and compare your options before placing it on the market.
You may also request a free consultation, send a message, call (239) 499-5068, or email laura@theflteam.com.
Official Sources and Helpful Resources
- Florida Statutes, Section 689.302: Flood Disclosure
- EPA: Disclosures Concerning Potential Lead-Based Paint Hazards
- HUD: Fair Housing
- FBI IC3: Business Email Compromise
The information in this article is general and educational. It does not constitute legal, tax, insurance, construction, title, or financing advice for any particular situation. Obligations and costs depend on the property, contract, jurisdiction, association, insurance company, and loan program. Consult the appropriate licensed professionals before making a decision or signing documents.
Categories
Recent Posts
${companyName}
Phone