- /
How to Build Wealth From Your First Home: A Guide for Young Couples Starting From Zero
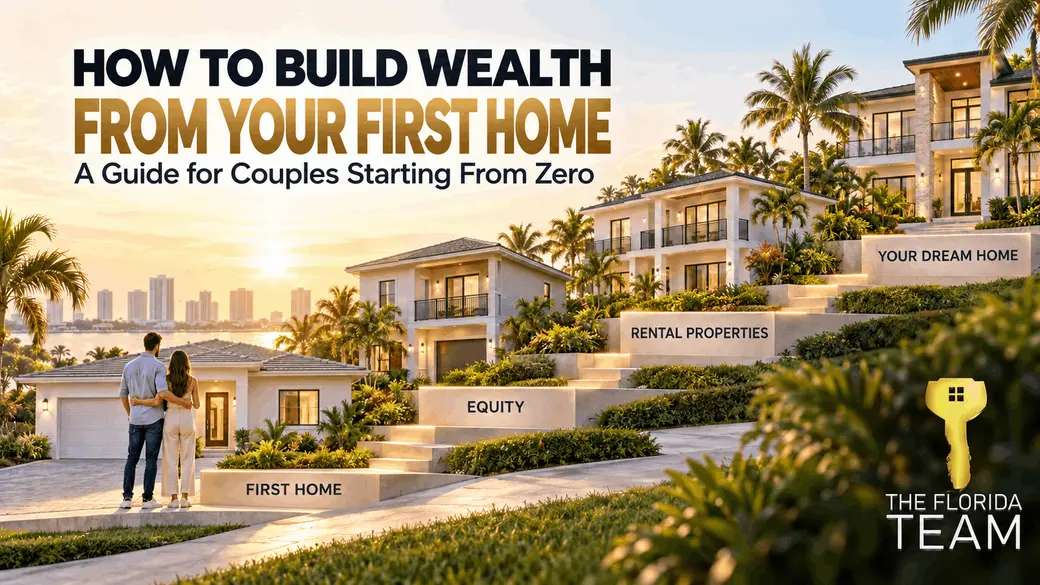
If you and your partner did not inherit a house, land or a large amount of money, that does not mean you are too late. It simply means you will need to build your wealth intentionally.
For many young couples, a first home can be much more than the place where they begin their life together. It can become the first asset in a strategy that, with discipline and time, may allow them to purchase a second home, keep a rental property, acquire a third property and create a financial foundation that did not previously exist in their family.
The key is not starting with the perfect home. It is starting with a property you can afford, maintain and use as a stepping-stone toward your next goal.
Quick answer: To build wealth from your first home, buy below your maximum purchasing power when possible, select a property with resale or rental potential, maintain adequate reserves, improve the home strategically and decide early whether your next step will be to sell, rent or purchase a multifamily property. Appreciation is never guaranteed. Long-term stability is built through equity, cash flow, time and responsible decisions.
You can begin by searching available Florida properties, exploring new construction homes or estimating your payment with our Florida mortgage calculator.
Important: This guide is educational and does not constitute legal, tax, financial or investment advice. Property values, rents, interest rates, taxes, insurance and other costs can change. Every purchase should be evaluated individually.
Your First Home Does Not Have to Be Your Dream Home
One of the most common mistakes young couples make is waiting until they can purchase their forever home: four bedrooms, a pool, a remodeled kitchen, the ideal location and enough room for everything they do not yet own.
While they wait, they continue paying rent and postpone building a history as homeowners. But a first property can serve a different purpose: it can be the first step.
A strategic first purchase might be:
- Smaller than you originally imagined.
- A townhouse instead of a detached home.
- A property that needs cosmetic improvements.
- A home with a room that can be rented legally.
- An eligible duplex, triplex or fourplex where you occupy one unit.
- A property in a growing area, even if it is not your final location.
This does not mean buying just any property. It means understanding the difference between the home you want forever and the asset that may help you reach it.
What Does Building Wealth Through a Home Actually Mean?
Real estate wealth is not simply owning a house. Home equity is the difference between what the property is worth and what you still owe, after considering the costs required to sell or refinance.
Equity may grow in four ways:
- Mortgage amortization: Part of each payment reduces the principal balance.
- Appreciation: The property may increase in value over time, although appreciation is never guaranteed.
- Strategic improvements: Certain renovations may improve value, function or rental potential.
- A strong purchase: Buying at a reasonable price, negotiating credits or selecting an area with demand may improve your starting position.
The goal is not to brag about the value of the property. The goal is to responsibly convert equity into future options.
The CASA Method for Couples Starting From Zero
The CASA Method provides a simple framework for moving from a first home toward a stable real estate portfolio.
C — Choose Strategically, Not Emotionally
Before touring homes, decide together:
- The monthly payment you can maintain even during difficult months.
- How much cash will remain after closing.
- What it will cost to maintain the property.
- Whether the home is likely to have future rental demand.
- Which improvements you can make without taking on excessive debt.
- Whether the HOA permits rentals and under what conditions.
- How easy the property may be to resell as your life changes.
A lender may approve you for more than is wise for your long-term plan. If your first purchase uses all your financial capacity, saving, investing or qualifying for another property may become much harder.
The right question is not only, “How much can we qualify for?” It is, “Which purchase allows us to live comfortably while continuing to grow?”
A — Achieve Stability First
A house does not create financial freedom if every repair becomes an emergency. Before thinking about a second property, build a foundation:
- A personal emergency fund.
- Reserves specifically for the home.
- Adequate insurance and a deductible you can afford.
- Consumer debt under control.
- Protected credit.
- Automatic monthly savings.
- A maintenance plan for the roof, HVAC, plumbing and other major systems.
Do not use every dollar for the down payment. Moving expenses, repairs, utility deposits and other costs appear soon after closing, even when they were not visible in the listing photos.
S — Step Up to the Next Property
When income, reserves and equity allow, you may choose among several paths:
- Keep the first home and convert it into a rental.
- Sell it and use the equity to purchase a property with greater potential.
- Begin with an owner-occupied multifamily property.
- Purchase a second property directly as an investment.
- Repeat a purchase, improvement and primary-residence strategy when legally and financially appropriate.
There is no perfect route for every couple. The right path depends on income, debt, equity, potential rent, the market and your tolerance for risk.
A — Accumulate Assets Without Losing Liquidity
Owning three properties with unmanageable payments is not necessarily better than owning one solid property, maintaining strong reserves and preserving the ability to take advantage of future opportunities.
Sustainable growth requires:
- Realistic cash flow.
- Reserves for every property.
- Maintenance and vacancy included in your calculations.
- Properly projected taxes and insurance.
- Financing that does not depend on a perfect scenario.
- Separation between personal and property finances.
- A team that may include a REALTOR®, Loan Officer, CPA, attorney, insurance agent and property manager.
How to Buy Your First Home With a Low Down Payment
Buying with a small down payment does not mean buying without preparation. Certain programs may reduce the amount required upfront, but you still need to budget for inspections, appraisal, earnest money, insurance, closing costs and reserves.
Options That May Allow a Lower Down Payment
| Option | Potential advantage | What to evaluate |
|---|---|---|
| FHA | Down payment starting at 3.5% for eligible buyers | Mortgage insurance and property requirements |
| Conventional with 3% down | Available through certain programs to qualifying buyers | Credit, income, occupancy and mortgage insurance |
| VA | May allow 0% down for eligible veterans | Eligibility, funding fee and loan requirements |
| USDA | May allow 0% down in eligible areas | Income and location limits |
| Down payment assistance | May help with down payment or closing costs | Funding, eligibility, secondary liens and future conditions |
| Seller concessions | May reduce some cash needed at closing | Must be negotiated and remain within program limits |
| Gift funds | Eligible relatives may assist under certain programs | Documentation and program-specific rules apply |
HUD generally requires a minimum investment of 3.5% for FHA borrowers, which may come from acceptable sources under the program guidelines. Freddie Mac offers options such as HomeOne® and Home Possible® with down payments as low as 3% for qualifying buyers.
A low-down-payment purchase works best when the cash not used for the down payment remains in reserves or serves another strategic purpose. It works poorly when the couple is left with no cash after closing.
Three Paths From Your First Home to Your Second
Path 1: Keep the First Home and Convert It Into a Rental
This strategy may allow a couple to purchase another primary residence while keeping the first property as a rental asset.
Before relying on rental income, calculate:
- Conservative monthly rent supported by actual comparable rentals.
- Vacancy.
- Property management, even if you initially plan to manage it yourself.
- Repairs and routine maintenance.
- HOA fees and rental restrictions.
- Property taxes after any applicable benefits change.
- Landlord insurance and flood insurance when needed.
- Local registration or licensing costs.
- The complete mortgage payment.
Estimated cash flow:
Rent − complete mortgage payment − HOA − management − vacancy − maintenance − other expenses = estimated cash flow
If the property only makes money when nothing breaks and it is never vacant, it does not have strong cash flow.
To qualify for the next mortgage, the lender will determine how much rental income can be counted and what documentation is required. Do not assume 100% of the rent will be used for qualification.
When Keeping the First Home May Make Sense
- Rent reasonably covers expenses and leaves a margin.
- The area has consistent rental demand.
- You have sufficient reserves for two properties.
- The HOA permits rentals.
- The property does not need an immediate major repair.
- Keeping it does not prevent you from comfortably purchasing the next home.
When Selling May Be the Better Choice
- You need the equity for the next down payment.
- The rent does not cover the property’s true costs.
- A major repair would consume your reserves.
- The association limits or prohibits rentals.
- Managing the property would undermine your stability or other goals.
Path 2: Sell and Reinvest the Equity
Selling your first home does not mean abandoning the strategy. In some cases, it is the most efficient way to release capital for a better-located property, a multifamily purchase or a home with stronger long-term potential.
The result of a sale is not simply the sales price minus the mortgage balance. Consider:
- Remaining loan balance.
- Commissions and selling expenses.
- Repairs or buyer credits.
- Prorations, taxes and title costs.
- Potential tax consequences.
The IRS allows certain homeowners to exclude up to $250,000 of gain, or up to $500,000 for many married couples filing jointly, when applicable eligibility requirements are satisfied. Generally, the ownership and use tests consider whether the property was owned and used as a primary residence for at least two of the five years before the sale. Consult a CPA before basing your strategy on this exclusion.
Path 3: House Hacking
House hacking means living in one part of a property while another part helps offset the housing payment. It may involve:
- A duplex, triplex or fourplex.
- A legally rented bedroom.
- A permitted independent suite.
- A legal accessory dwelling unit where local rules permit it.
The advantage is that a couple can begin as homeowners and future investors through a single purchase. Income from other units or spaces may reduce the net cost of housing.
However, you must verify:
- Legal use and zoning.
- Permits.
- Privacy and safety.
- Appropriate insurance.
- Loan occupancy requirements.
- Rental income eligible for qualification.
- Maintenance of multiple units.
- Landlord-tenant and fair housing laws.
Do not call an unpermitted conversion a legal unit. An additional kitchen or separate entrance does not guarantee that the space can be rented lawfully.
Moving From the Second Property to the Third
The third purchase should not happen simply because the second closing went well. Before repeating the process, review the portfolio like a business.
The Financial Traffic Light
Green:
- Stable income.
- Personal emergency reserves remain intact.
- Separate reserves for every property.
- Strong payment history.
- Proven cash flow or manageable total housing payments.
- Current insurance, taxes and maintenance.
- Ability to withstand a vacancy or major repair.
Yellow:
- Rent barely covers the mortgage.
- Credit cards are being used for repairs.
- You depend on overtime or inconsistent bonuses.
- The next down payment would empty your savings.
- Future taxes and insurance have not been calculated.
Red:
- Late payments.
- Increasing consumer debt.
- No reserves.
- Properties with deferred maintenance.
- The plan requires an immediate refinance to work.
- The purchase is based only on the belief that prices always rise.
If you are in the yellow zone, strengthen the foundation. If you are in the red zone, pausing may be wiser than buying.
A Simple Example: A Couple Beginning Without an Inheritance
Imagine a couple purchasing a $350,000 home with a 3% down payment program.
- Illustrative down payment: $10,500.
- Earnest money and closing costs are calculated separately.
- They preserve an emergency fund after closing.
- They buy a functional home rather than a completely remodeled one.
- They improve paint, lighting and exterior appearance without financing major purchases.
- Over several years, they reduce the principal balance and grow their income.
Later, they evaluate three possible decisions:
- Keep it: If it can be rented with a reasonable margin and they have sufficient reserves.
- Sell it: If the net equity can help them move to the next level.
- Stay: If another purchase would threaten their financial stability.
This example does not assume appreciation, a particular interest rate or guaranteed profit. It demonstrates that a low down payment may open the door, but wealth is built after closing through time, discipline and sound decisions.
How Couples Should Divide Financial Responsibilities
The plan should be shared even if one partner earns more or has stronger credit.
Before buying, discuss:
- Who will be on the mortgage and who will hold title.
- How each person will contribute to the down payment and reserves.
- What will happen if one person loses a job.
- How much either person can spend without consulting the other.
- Who will manage payments, repairs and records.
- Your goals for the next 2, 5 and 10 years.
- What would happen to the property after separation, disability or death.
Marriage does not replace estate planning. Consult an attorney about title, agreements, estate planning and legal protection, and consult a CPA regarding taxes.
Improvements That May Help—and Improvements That May Hold You Back
Not every renovation creates equity. Some improvements increase functionality or appeal but do not recover their full cost.
Prioritize
- Repairs that prevent greater damage.
- Roof, plumbing, electrical and HVAC work when necessary.
- Neutral paint and exterior maintenance.
- Functional lighting.
- Layout and storage improvements.
- Updates that improve insurability, resale or rental potential.
- Permits and corrections to previous unpermitted work.
Avoid at the Beginning
- Luxury renovations financed with credit cards.
- Highly personalized changes.
- Buying furniture before closing.
- Opening new accounts during the mortgage process.
- Spending reserves to make the house look perfect.
- Building an additional unit without confirming zoning and permits.
Should You Use Your Home Equity to Purchase Another Property?
A HELOC, home equity loan or cash-out refinance may provide access to equity, but it also converts part of the wealth you have accumulated into new debt secured by your home.
The Consumer Financial Protection Bureau warns that failing to repay debt secured by your home could result in losing the property and that no investment is risk-free. Before using equity for another purchase, compare:
- The new payment and any variable interest rate.
- Closing costs.
- Reserves remaining afterward.
- Conservative cash flow from the investment.
- Your ability to make payments during a vacancy.
- Alternatives involving less risk.
Equity is not free money. It is wealth you are placing at risk again.
Financial Rules That Protect the Plan
- Buy based on the complete monthly payment, not the price alone. Include principal, interest, property taxes, insurance, mortgage insurance, HOA fees and assessments.
- Maintain reserves after every closing. A property without reserves can quickly become credit-card debt.
- Do not rely on appreciation to rescue a poor purchase. Evaluate the property using today’s numbers.
- Use conservative rent estimates. Compare properties that actually rented, not only active listings.
- Budget for vacancy and maintenance. Even a newly built home requires money.
- Protect both partners’ credit. Late payments and new debt may close the door to the next purchase.
- Evaluate every property as if it were your only one. The number of doors does not replace asset quality.
- Do not mix every account. Maintain clear records for each property.
- Plan the exit before purchasing. Can the property be sold, rented or retained comfortably?
- Move forward when the numbers support it, not because of social comparison.
Action Plan: From Year 0 to Year 10
This timeline is a general framework, not a promise or a rigid rule.
Stage 1 — Preparation
- Review credit, debts, income and financial documents.
- Build an emergency fund.
- Establish a comfortable monthly payment.
- Obtain a mortgage preapproval.
- Compare low-down-payment programs.
- Select a property with current usefulness and future options.
Stage 2 — First Property
- Maintain a perfect payment history.
- Avoid unnecessary debt.
- Complete priority improvements.
- Learn the true costs of ownership.
- Save automatically for the next step.
Stage 3 — Evaluation
- Request a property value analysis.
- Estimate market rent and cash flow.
- Review the mortgage balance and net equity.
- Update your preapproval.
- Decide whether to keep, sell or remain in the home.
Stage 4 — Second Property
- Purchase only if both properties are sustainable.
- Separate reserves and financial records.
- Formalize management of the rental.
- Review insurance and legal structure.
Stage 5 — Stable Portfolio
- Repeat only when liquidity supports it.
- Diversify locations and risks intentionally.
- Review taxes and estate planning.
- Measure net worth, debt and cash flow annually.
Checklist Before Purchasing the Next Property
- We have a personal emergency fund.
- We have reserves for each property.
- The first home can be sold or rented legally.
- We calculated future taxes and insurance.
- We included vacancy, management and maintenance.
- Our credit remains stable.
- We can cover the payments without relying on appreciation.
- We understand the occupancy requirements of the new loan.
- We consulted about legal and tax consequences.
- The purchase advances our goals without sacrificing financial peace.
Frequently Asked Questions
Do We Need 20% Down to Get Started?
Not necessarily. Certain conventional loans may allow 3% down for eligible buyers; FHA may allow 3.5%; and VA or USDA financing may provide 0% down for qualifying borrowers. A lower down payment may result in a higher payment or mortgage insurance. Closing costs and reserves must also be budgeted.
Can We Buy Another Primary Residence and Rent Out the First?
Possibly. The lender must evaluate income, debts, reserves, occupancy and rental documentation. The HOA, insurer and local regulations must also permit the rental. Do not convert the property into a rental without making the required disclosures and updates.
How Long Should We Wait Before Buying the Second Property?
There is no universal waiting period. The answer depends on financial capacity, loan requirements, occupancy, equity, reserves and goals. Some couples wait several years; others begin with a multifamily property. Buying too quickly can destroy the stability the first home was supposed to create.
Is It Better to Sell or Keep the First Home?
Keeping it may make sense when the rent produces a margin and you have adequate reserves. Selling may be better when you need the equity, the rental numbers do not work or managing the property creates too much risk. The decision should be based on the net result rather than emotional attachment.
Can Rental Income Be Used to Qualify?
In some cases, yes. However, the lender will apply program-specific rules and may use only a portion of the documented income. Treatment varies according to the loan, property and borrower experience.
Is Real Estate Always a Good Investment?
No. An overpriced property, difficult insurance, high fees, major repairs or insufficient rent can delay your progress. Real estate can lose value and produce unexpected expenses.
Your First Home Can Change Your Family’s Financial Story
People who inherit wealth begin with an advantage. People starting from zero need a strategy.
Your first property may not have the dream kitchen, pool or final neighborhood. But it may give you something more important: stability, experience, equity and options.
This is not about purchasing three homes as quickly as possible. It is about building a foundation strong enough that each property makes the next step easier—not harder.
As both a REALTOR® and Mortgage Loan Originator, I can help you evaluate the purchase and financing as one coordinated strategy: how much to spend, which property type to consider, what expenses to anticipate and which future options the first purchase may provide.
Start With a Personalized Plan
- Request a complimentary consultation.
- Search available Florida properties.
- Explore new construction homes in Florida.
- Call or text (786) 574-3005.
- Email laura@theflteam.com.
About the Author
Laura Rojas, REALTOR® and Mortgage Loan Originator
CEO and Team Leader, The Florida Team by LPT Realty
Florida Real Estate License: SL3454829
NMLS: 2619252
Phone: (786) 574-3005
Email: laura@theflteam.com
Website: laurarojasrealtor.com
Laura helps buyers, sellers and investors turn complex real estate decisions into clear plans. Her approach combines real estate representation with mortgage strategy so clients understand not only how much they can purchase today, but also how that decision may support their future financial stability.
Official Sources and Resources
- HUD: Buying a Home and FHA Loans
- HUD: FHA Minimum Required Investment
- Freddie Mac HomeOne®
- Freddie Mac Home Possible®
- Freddie Mac: Mortgages for Two- to Four-Unit Properties
- IRS Publication 523: Selling Your Home
- IRS: Tax Considerations When Selling a Home
- CFPB: What Is a HELOC?
- CFPB: Risks of Home Equity Loans
Disclaimer
The information in this guide is provided for educational and informational purposes only. It does not constitute legal, tax, accounting, investment, financial, mortgage or insurance advice, nor is it a recommendation to purchase, sell, rent, refinance or use the equity in a property.
Property values, rents, interest rates, taxes, insurance premiums, maintenance costs, occupancy requirements, loan limits, assistance programs and underwriting guidelines may change. Appreciation, cash flow, mortgage approval and investment results are not guaranteed. Every real estate investment may lose value or generate losses.
Eligibility and final terms depend on the buyer, property, program, lender, insurer, association, county and conditions in effect at the time. A preapproval is not a final commitment to lend. Before making a decision, consult the appropriate professionals, including an attorney, CPA, tax advisor, insurance agent, inspector and Loan Officer.
Laura Rojas is a Florida-licensed REALTOR®, license SL3454829, and Mortgage Loan Originator, NMLS 2619252. Services are offered in accordance with applicable licenses, affiliations and disclosures. Equal Housing Opportunity.
Recent Posts
${companyName}
Phone